Does homeowners insurance cover fire damage restoration in Edwards
Yes, most homeowners insurance policies in Edwards cover fire damage restoration, including smoke and soot removal. Here's how claims work and what to watch for.
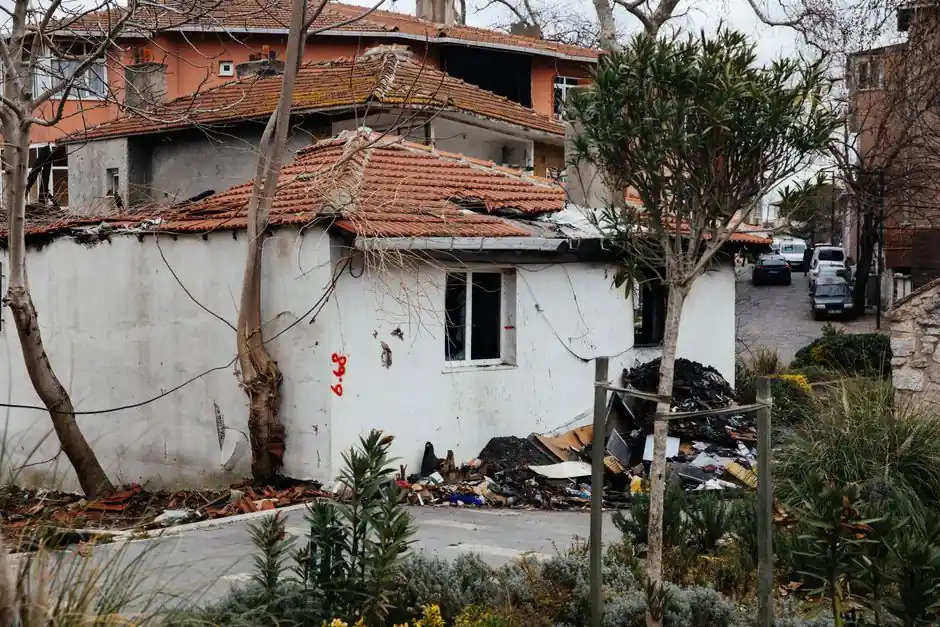
Yes, homeowners insurance covers fire damage restoration in Edwards, California, in most standard policies. If your home is damaged by a fire, your insurer typically pays to repair the structure, replace damaged belongings, and clean up smoke and soot, up to your policy limits and minus your deductible. The rest of this post explains what's covered, how to file a claim, what to do if your claim is denied, and how to avoid the mistakes that cost homeowners thousands.
Does homeowners insurance cover fire damage restoration in Edwards?
Homeowners insurance fire damage coverage in Edwards, California, is one of the broadest protections your policy offers. A standard HO-3 policy covers fire damage to the dwelling, other structures on the property, personal belongings, and loss of use (hotel and meals while your home is uninhabitable). Fire is a named peril, so there's no arguing about whether the cause is covered unless the fire was intentional or resulted from certain excluded activities.
What many homeowners miss is that "fire damage" includes more than charred wood. Smoke travels through ductwork and settles into insulation, soot etches glass and metal, and water from firefighting efforts can soak drywall and framing. Your policy generally covers all of that, but only if you document it properly and work with a restoration company that knows how to write a scope your adjuster will approve.
If you're searching for fire damage restoration near me in EDWARDS, California, make sure the company you hire understands insurance claims. The restoration estimate is the backbone of your claim, and a vague or inflated estimate slows everything down.
What your policy actually covers after a fire
What does homeowners insurance cover after a fire in Edwards California? It covers four main buckets: the structure, your personal property, additional living expenses, and debris removal. Each has its own limit, and those limits are where claims get complicated.
Dwelling and other structures
This is the big one. Your dwelling coverage (Coverage A) pays to repair or rebuild the house itself. Other structures coverage (Coverage B) handles detached garages, sheds, and fences. In Edwards, where many homes sit on larger lots with detached shops or carports, that separate limit matters. A typical policy sets other structures at 10% of the dwelling limit, so a $400,000 dwelling policy gives you $40,000 for the shop out back.
Personal property
Coverage C pays to replace or repair furniture, clothing, electronics, and appliances. Most policies cover personal property at 50-70% of the dwelling limit. There are two big caveats: high-value items like jewelry and firearms often have sub-limits (sometimes $1,500-$2,500), and actual cash value policies deduct depreciation, so a 10-year-old sofa pays out far less than a new one.
Loss of use
If your home is uninhabitable, Coverage D pays for hotel bills, restaurant meals, and other increased living costs. In Edwards, where rental inventory is tight, this coverage is critical. Most policies cap loss of use at 20-30% of the dwelling limit and limit the time period, often 12-24 months.
Debris removal and smoke damage
Debris removal is usually included, often with a sub-limit of 5-10% of the dwelling coverage. Smoke damage cleanup is covered as part of the fire claim, but you need to document it thoroughly. Smoke residue is acidic and continues to damage surfaces for weeks, so waiting to file can reduce your payout. Our smoke damage restoration in EDWARDS, California team documents every affected room before we start cleaning.
How to file a fire damage insurance claim in Edwards
Filing a fire damage insurance claim in Edwards follows a predictable sequence, and the order you do things matters. Here's the process we walk homeowners through every week.
- Secure the property and call your insurer. Report the claim the same day. Most policies require prompt notice, and delays give the adjuster room to question the damage.
- Document everything before cleanup. Photograph every room, every damaged item, and every receipt. Don't throw anything away until the adjuster has seen it or your restoration company has inventoried it.
- Get a professional scope of damage. A restoration company will write a room-by-room estimate using industry-standard pricing (Xactimate is common). This becomes the basis for your claim.
- Meet the adjuster on site. Be there. Walk the adjuster through the damage with your contractor's estimate in hand. Discrepancies get resolved faster when everyone is looking at the same wall.
- Review the settlement and negotiate if needed. You are not required to accept the first offer. If the scope misses items, ask for a supplement.
One local detail: Edwards sits in the high desert, and the dry air and wind can push smoke residue deeper into a structure than you'd expect. If your home is in an older neighborhood like Fire Damage Restoration in Downtown Edwards, where homes often have original plaster and older ductwork, the smoke cleanup scope needs to account for that. We see claims underpaid when the adjuster writes a surface-cleaning scope for a house that needs duct cleaning and insulation replacement.
How much does homeowners insurance pay for fire damage in Edwards?
How much homeowners insurance pays for fire damage in Edwards depends on your policy limits and the extent of the damage, but typical payouts range from a few thousand dollars for a contained kitchen fire to full dwelling limits for a total loss. A small kitchen fire with smoke damage often settles between $8,000 and $25,000. A fire that damages the roof and attic can run $50,000-$150,000. A total loss pays up to your dwelling limit.
Your deductible comes off the top. In California, common deductibles run $1,000-$5,000, and some wildfire-prone areas carry percentage deductibles (1-2% of the dwelling limit). Edwards is not in a high wildfire severity zone like the foothills, but insurers have tightened underwriting across the state, so check your declarations page.
For 2026 pricing, restoration costs in Edwards run roughly $3,000-$8,000 for a small kitchen fire cleanup, $10,000-$30,000 for moderate smoke and soot damage across a floor, and $50,000+ for structural repairs. Your insurance payout is based on the scope, not a flat rate, so the quality of the estimate matters more than the headline number.
If you're also dealing with water damage from firefighting, our fire and flood restoration in EDWARDS, California service handles both in one claim, which prevents the two adjusters from pointing fingers at each other.
What if my fire damage claim is denied in Edwards California?
What if my fire damage claim is denied in Edwards California? You can appeal. A denial is not the final word. Common reasons for denial include missed deadlines, insufficient documentation, disputed cause, or a policy exclusion (like intentional acts or vacant-home exclusions).
Start by reading the denial letter carefully. It must cite the policy language. Then request a copy of the adjuster's report and compare it to your contractor's scope. If the denial is based on cause, get a fire marshal report or an independent cause-and-origin investigation. If it's based on scope, a supplement request with photos and line-item pricing often reverses the decision.
You can also file a complaint with the California Department of Insurance, which regulates homeowners insurers in the state. That step alone sometimes prompts a re-review. If the amount in dispute is significant, a public adjuster works on contingency (typically 10-15% of the settlement) and can handle the appeal for you.
Don't let a denial stop the cleanup. Smoke and soot damage gets worse every day. Call a restoration company to stop the damage while you fight the claim. Our emergency fire damage restoration in EDWARDS, California team can board up, tarp, and start mitigation the same day.
Common mistakes that hurt your fire damage claim
Most underpaid fire claims in Edwards trace back to a handful of avoidable mistakes. Watch for these.
- Cleaning before documenting. Once soot is wiped away, the adjuster can't see the spread. Photograph first.
- Throwing away damaged items. Your personal property claim needs evidence. Keep a pile until the adjuster signs off.
- Hiring a contractor who doesn't write insurance scopes. A generic bid that says "repair fire damage: $20,000" gets kicked back. Line-item estimates get approved.
- Missing the smoke damage in the HVAC system. Smoke pulls through returns and coats the blower and ducts. If the scope doesn't include duct cleaning, you'll smell the fire every time the heat kicks on.
- Waiting too long to file. Policies require prompt notice. A delay of weeks gives the insurer grounds to reduce or deny the claim.
We see this often in Fire Damage Restoration in Edwards Village, where homes are close together and smoke from a neighbor's fire can enter through attic vents. If your home smells like smoke but you didn't have a fire, check with your neighbor and document the date. Your policy may still cover the cleanup under a smoke damage provision.
When to call a professional
Call a professional when the fire has damaged anything beyond a single room, when smoke odor persists after ventilation, or when you're filing an insurance claim. DIY cleanup rarely satisfies an adjuster, and improper soot removal can spread residue and void coverage. Our team at Fire Damage Restoration Edwards handles the documentation, the cleanup, and the communication with your adjuster so you're not translating between contractor and insurer.
If you need fire damage clean up in EDWARDS, California, we start with a room-by-room assessment and a written scope you can hand to your insurer. We also handle soot removal in EDWARDS, California and duct cleaning, which are the two line items most often missing from initial claim estimates.
Frequently Asked Questions
Does homeowners insurance cover fire damage restoration in EDWARDS California?
Yes. Standard homeowners policies in Edwards cover fire damage restoration, including structural repairs, smoke and soot cleanup, and personal property replacement, up to your policy limits and minus your deductible. Fire is a named peril, so coverage is broad unless the fire was intentional or the policy has a specific exclusion.
How much does homeowners insurance pay for fire damage in EDWARDS?
Payouts range from about $8,000 for a contained kitchen fire to your full dwelling limit for a total loss. A moderate fire with smoke damage across one floor often settles between $25,000 and $75,000. Your deductible and policy limits determine the final amount.
What if my fire damage claim is denied in EDWARDS California?
You can appeal a denial. Request the adjuster's report, compare it to your contractor's scope, and submit a supplement with photos and line-item pricing. If that fails, file a complaint with the California Department of Insurance or hire a public adjuster to handle the appeal.
Does insurance cover smoke damage cleanup in EDWARDS?
Yes. Smoke damage cleanup is covered as part of a fire claim. That includes surface cleaning, duct cleaning, insulation replacement, and odor removal. Document the smoke spread before cleaning, because the adjuster needs to see the affected areas to approve the scope.
Will insurance pay for a hotel while my home is being restored?
Yes, if your home is uninhabitable. Loss of use coverage pays for hotel, meals, and other increased living costs, typically up to 20-30% of your dwelling limit and for a limited time, often 12-24 months. Keep every receipt.
Get help with Fire Damage Restoration in EDWARDS
If you're dealing with fire damage and an insurance claim, we can help. Fire Damage Restoration Edwards handles the cleanup, the documentation, and the back-and-forth with your adjuster so your claim moves forward. Call us at (833) 929-6186 to schedule an assessment.